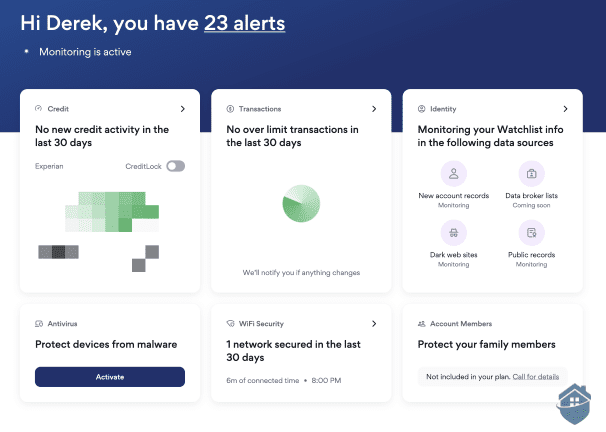
Shopping for identity theft protection can feel like a lot. Every provider claims to watch “everything,” and the plans start to blur together when comparing advertised features. Coveron, from Nord Security, is actually one of the more straightforward options out there. It keeps an eye on your personal information, and if something does slip through, it backs that up with real insurance money rather than just a promise to “help.” You may recognize the name from its previous life as NordProtect. It’s the same service with a new name.
We put together this guide to walk through exactly what you’re getting (and not getting) with each Coveron plan. There are big differences that significantly impact your coverage between tiers with more nuance than it seems at first glance. If you’d rather zoom out and compare your options more broadly first, our best identity theft protection roundup is a good place to start.
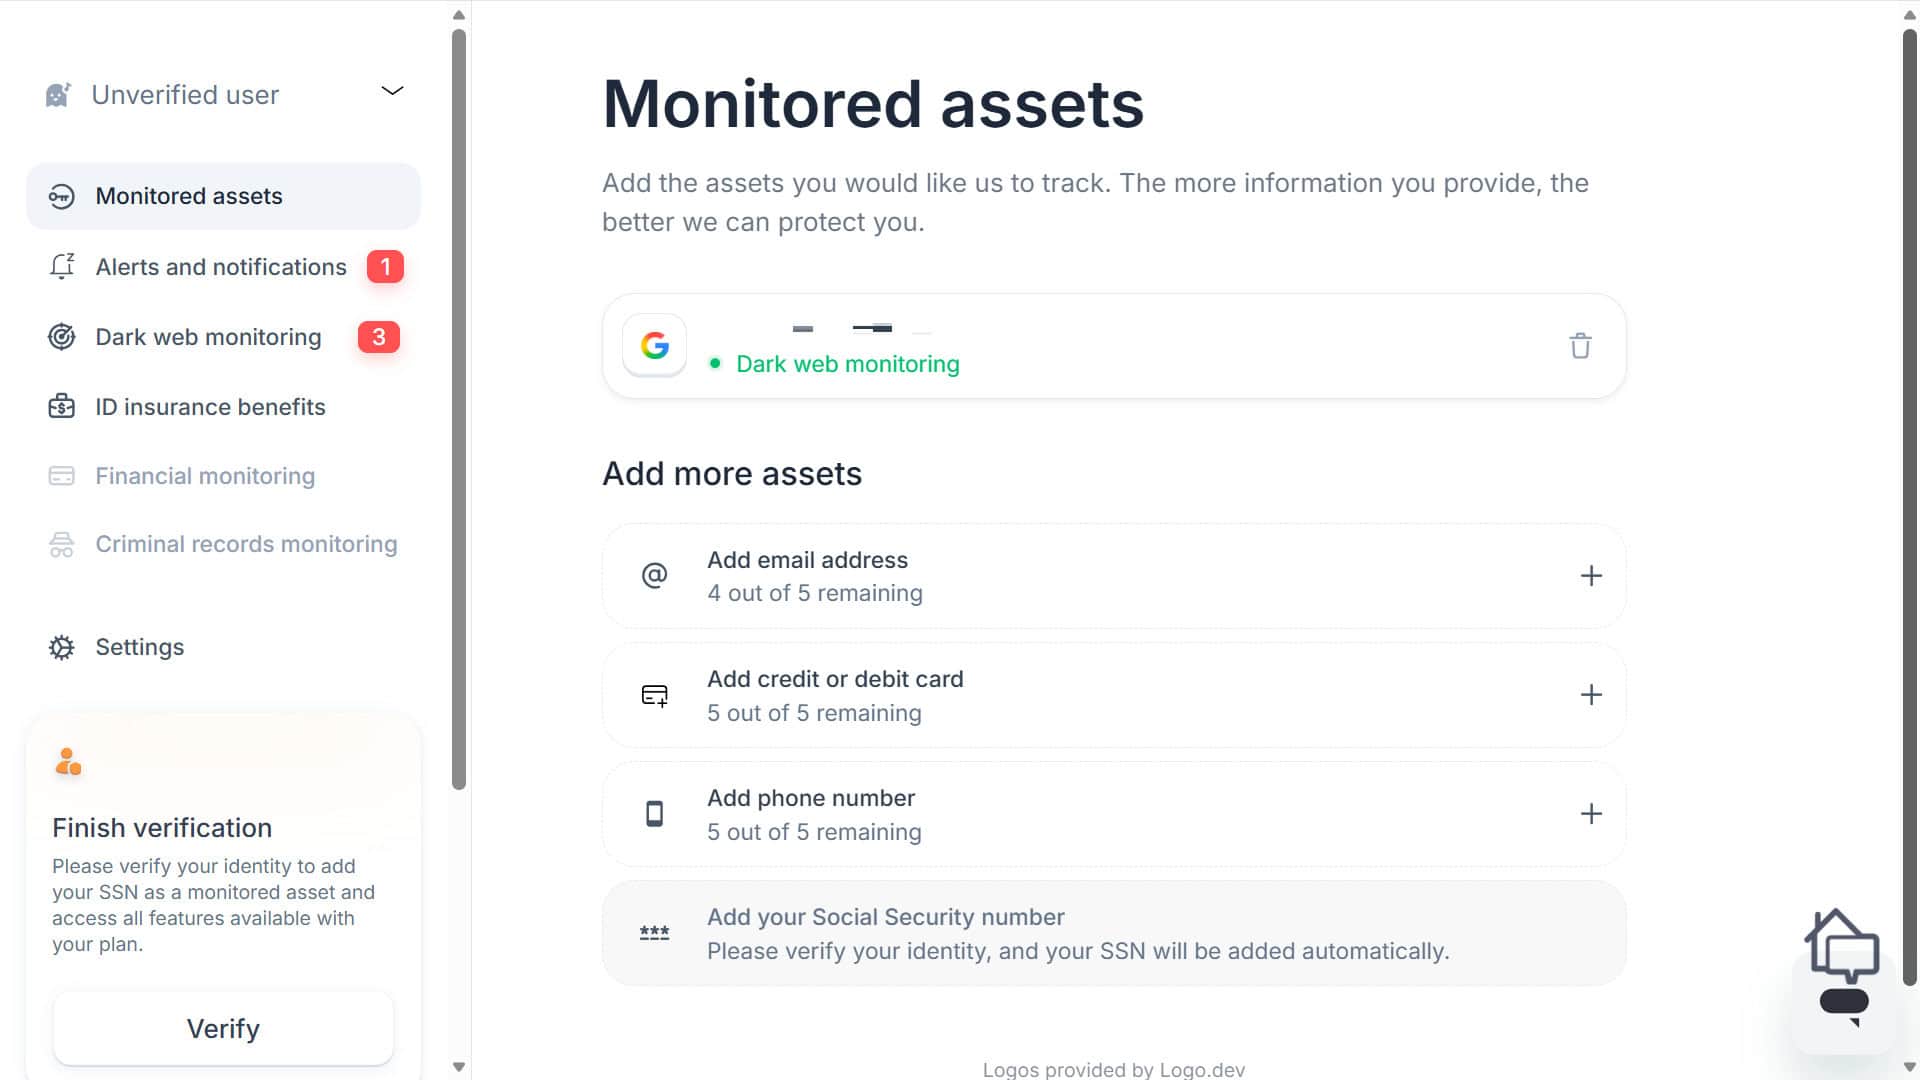
Coveron makes it easy to add email addresses, credit or debit cards, and phone numbers for monitoring
Coveron Plans and Pricing
Coveron sells three individual plans and two family plans. Here’s the full monthly-equivalent breakdown by term length.
Plan
2-Year
1-Year
1-Month
Scam Protection
$4.74/mo
$5.69/mo
$12.49/mo
Identity Theft Protection
$6.64/mo
$7.59/mo
$18.49/mo
Full Protection
$10.44/mo
$11.39/mo
$30.49/mo
Full Couple Protection (2 adults + kids)
$17.09/mo
$18.99/mo
Not offered
Full Family Protection (5 adults + kids)
$26.59/mo
$28.49/mo
Not offered
Coveron’s pricing is one of the more straightforward plan structures we’ve seen in identity theft protection services. There are three individual tiers that scale in features and price, plus couple and family plans built from the top-tier individual plan.
There are a couple of things worth noting, though. First, these are first-term promotional rates, billed upfront for the 1-year and 2-year options. Renewal prices come in at roughly double the first-term promotional rates, depending on the specific plan you choose. That said, the 2-year term gets you the lowest monthly cost across every plan and on renewal, so we’d recommend it over the monthly or 1-year options. You’ll still get 30 days to test it out risk-free thanks to Coveron’s 30-day money-back guarantee on all plans. Not to mention, monthly billing isn’t available at all for Full Couple or Full Family Protection, so a family plan means committing to at least a year either way.
The jump from Scam Protection to Identity Theft Protection is a big one, so it’s worth paying attention to what each tier actually includes below.
Scam Protection
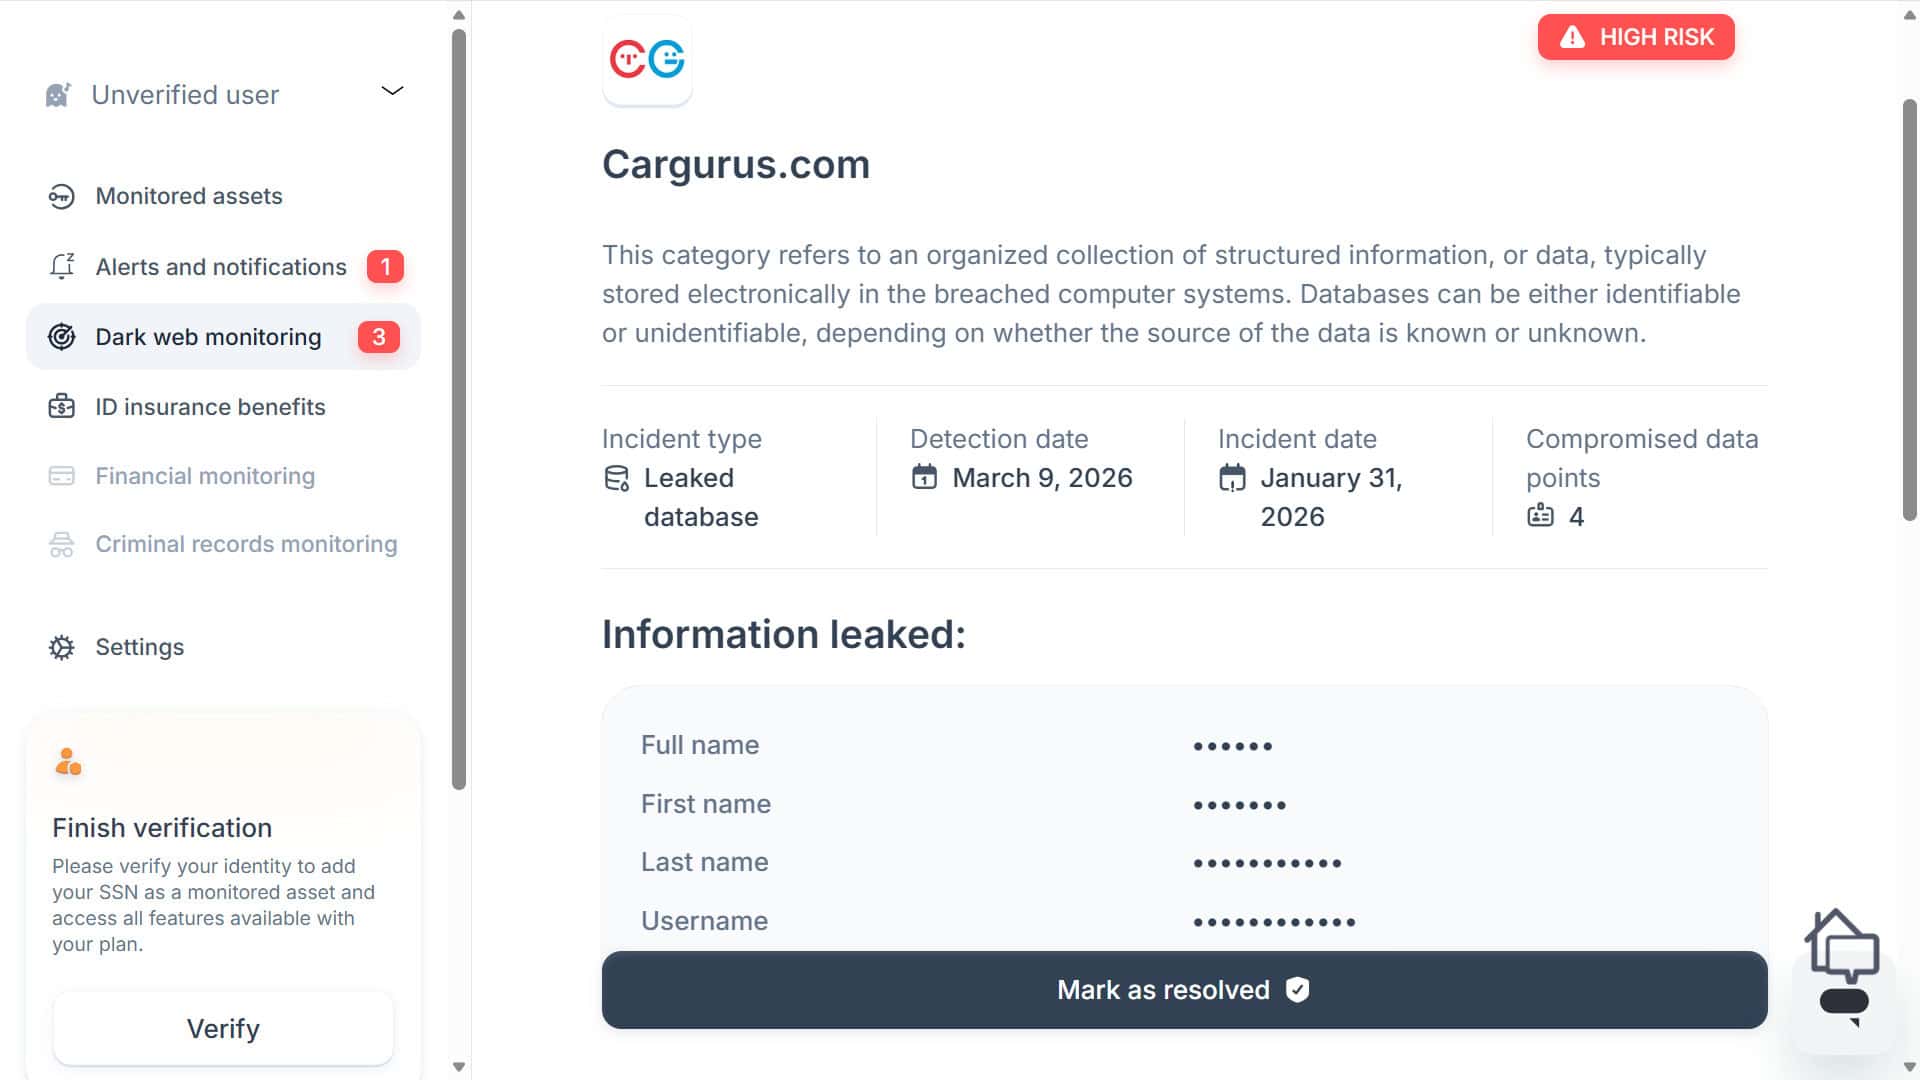
Coveron’s dark web monitoring alerts tell you the exact pieces of your information that were exposed
This is the plan we’d skip for most people. It’s a lightweight, breach-alert tier rather than full identity protection. It only includes:
$100,000 online fraud insurance
$10,000 cyberattack insurance
Dark web monitoring
Malware breach alerts
It skips identity theft insurance and credit monitoring entirely. If your main goal is knowing when your information leaks and having a small cushion for fraud losses, this covers that. But if you want the identity restoration and insurance backing that most people are actually shopping for when they search for a service like this, we’d recommend skipping straight to Identity Theft Protection instead.
Personal Experience: While most identity theft protection services offer dark web monitoring, we found Coveron’s more thorough than most competitors. It discovered a leak of our tester’s phone number that every other service they tested missed.
Identity Theft Protection
We’d point most people toward this tier, since it’s where Coveron’s insurance package actually kicks in, and it’s substantial. Most competitors, including Aura, cap real identity theft insurance around $1 million. Coveron doubles that at $2 million, on its second-cheapest plan, plus adds a few additional coverages that don’t count against that limit, like cyber extortion and home title fraud. Here’s an overview of what the plan includes:
$2 million identity theft insurance
$100,000 cyber extortion insurance
$100,000 home title fraud insurance
$100,000 online fraud insurance
$10,000 cyberattack insurance
1-bureau credit monitoring and credit score tracking (TransUnion)
Credit lock for TransUnion and credit freeze assistance for all three bureaus
Short-term/payday loan monitoring
Financial account monitoring
Criminal records monitoring
The cyber extortion coverage alone is worth calling out. Most identity theft protection services don’t insure against it specifically, and Coveron builds it into every tier above Scam Protection. The one caveat we’d flag before you commit here is that credit monitoring is limited to a single bureau (TransUnion) at this tier. If credit monitoring is your priority, we recommend the jump to Full Protection which expands coverage to three-bureau monitoring.
Expert Insight: The limited credit monitoring in the Scam Protection and Identity Theft Protection plans can seem like a major drawback. However, you can monitor your own credit for free. All three bureaus allow you to request a free credit report on a weekly basis through AnnualCreditReport.1 That’s all you need to spot suspicious activity.
Full Protection
This is the tier to pick if that single-bureau limitation from Identity Theft Protection is a dealbreaker, since it adds full three-bureau monitoring. It also carries the same insurance figures as Identity Theft Protection, but the monitoring and bundled tools get a real upgrade. We mainly recommend this plan for people who already pay for a VPN, antivirus, or data removal service separately. Here’s what it includes:
An annual three-bureau credit report and credit score update
Everything in Identity Theft Protection
NordVPN included
Next-gen antivirus included
Incogni personal data removal included
We’d recommend running the math on what you’re currently paying for those tools separately. If it adds up to more than the roughly $4 per month jump from Identity Theft Protection, Full Protection is the better deal.
Surprising Drawback: After testing Full Protection, we realized you only get an annually updated credit score, but it’s a three-bureau credit score. The Identity Theft Protection plan provides monthly updates to your one-bureau credit score. We prefer three-bureau coverage with less frequent updates, but it’s a tradeoff worth considering if you need to regularly check your credit score.
Full Couple Protection & Full Family Protection
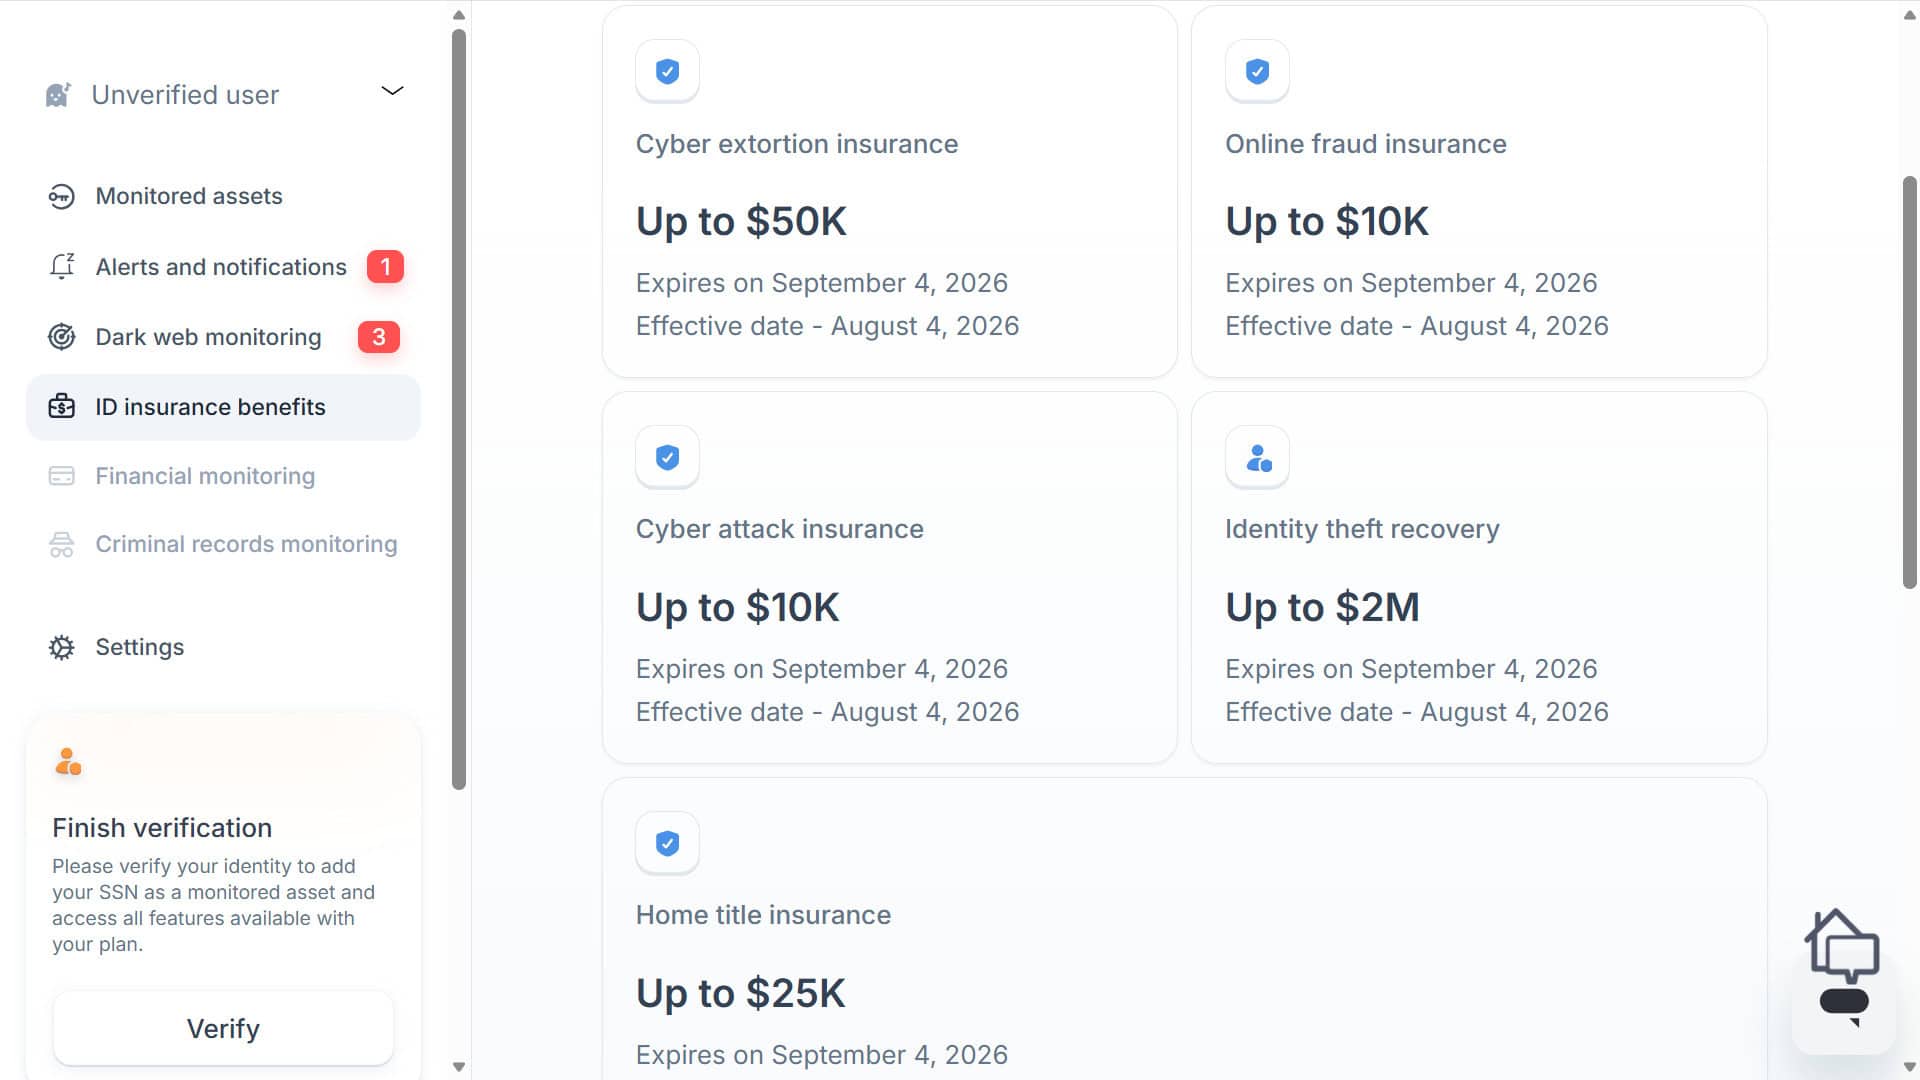
Family plans include the same insurance coverage as the Full Protection plan we tested
Those three plans are built for individual users. If you have a family or a spouse to cover, Coveron extends the Full Protection plan into two dedicated plans built for more users. Full Couple covers 2 adults and unlimited children, while Full Family covers up to 5 adults and unlimited children.
If you’re weighing a family plan, know that the $2 million identity theft insurance is a shared limit for all covered adults, not $2 million per person. That’s actually below the norm for family plans. Aura, for comparison, provides a $1 million policy for each of the up to five adults the plan supports. Any more than two adults on that plan brings the total over Cover’s $2 million total. That said, if you only need to cover two adults, a combined $2 million policy is better than $1 million per adult since you can use the full $2 million even if only one person’s identity gets stolen.
There’s another thing worth considering here. Kids on a Coveron family plan get dark web monitoring only (including SSN monitoring), while adults get the full plan’s benefits. That split actually lines up with how most family identity theft protection plans work. Kids typically get lighter monitoring than adults industry-wide. If you’re specifically shopping for family coverage, it’s worth comparing against our best family identity theft protection picks and, if it’s just the two of you, our best identity theft plans for couples.
A Closer Look at Coveron’s Features
We broke Coveron’s features down into the four areas that actually drive the buying decision:
How it watches for misuse of your identity
How it handles your credit
What happens if something goes wrong
Additional tools bundled in
Identity Monitoring
Identity theft isn’t a rare inconvenience anymore. The FTC’s Consumer Sentinel Network logged more than 1.1 million identity theft reports in 2024 alone, contributing to the $12.5 billion in total fraud losses reported that year.2 Many of those identity theft cases stem from data breaches that expose the personal information of hundreds of millions every year. That source of information continues to grow, seeing a nearly 80 percent jump over just five years.3 Against that backdrop, knowing when your information shows up somewhere it shouldn’t matters more than it used to.
Here’s an overview of the monitoring offered by Coveron across its three plans:
Feature
Scam Protection
Identity Theft Protection
Full Protection / Family Plans
Dark web monitoring
Yes
Yes
Yes
Malware breach alerts
Yes
Yes
Yes
Criminal records monitoring
No
Yes
Yes
Short-term/payday loan monitoring
No
Yes
Yes
Here’s how that plays out for you day to day. If your information turns up in a breach, Coveron catches it on every tier, including Scam Protection. But if someone opens a payday loan or shows up in a criminal background check under your name, you need Identity Theft Protection or higher to catch that. And if you’re covering kids on a family plan, their protection looks different from yours. They get dark web and SSN monitoring only, not the complete adult feature set. While kids are still at risk, it’s rarer than adult identity theft as we cover in our child identity theft statistics guide, so that reduction in coverage makes sense for most people.
FYI: Coveron also comes from the same company behind NordStellar, Nord Security’s separate threat-exposure monitoring product built for businesses rather than individual consumers. If you need exposure protection for your business, head over to our NordStellar review to see if it’s the right pick.
Credit Monitoring
We needed help from Coveron’s support to verify our identity and activate Coveron’s credit monitoring features
In practice, this comes down to which bureau is actually watching your back. On Scam Protection, none of them are, so a new account opened anywhere would slip through entirely. On Identity Theft Protection, you’re covered at TransUnion specifically, so if a lender only pulls your Equifax or Experian file, you won’t find out from Coveron. Full Protection and the family plans close that gap by watching all three. Here’s a quick comparison of all three plans:
Feature
Scam Protection
Identity Theft Protection
Full Protection / Family Plans
Credit bureaus monitored
None
1 (TransUnion)
3 (TransUnion, Experian, Equifax)
Credit lock
No
Yes (TransUnion)
Yes (TransUnion)
Credit score
No
1-bureau updated monthly
3-bureau updated annually
Credit freeze assistance
No
Yes
Yes
Annual 3-bureau credit report
No
No
Yes
Financial account monitoring
No
Yes
Yes
If comprehensive 3-bureau monitoring across every tier is non-negotiable for you, it’s worth cross-shopping our best credit monitoring services page. For instance, all of Aura’s plans include full three-bureau monitoring, and LifeLock’s plans offer at least two-bureau monitoring. Both also offer plans with an antivirus if device protections are also important to you.
We will note that we had issues activating the credit monitoring included in our plan. Most competitors automatically activated it after we signed up, however, Coveron struggled to verify our identity to tie it to our credit files. With the help of Coveron’s support, we got it working by providing them with additional information like our previous addresses.
What you’re actually paying for above Scam Protection is peace of mind backed by real money. If you’re ever hit with legal fees, lost wages, or a fraudulent loan taken out in your name, you’re not filing a claim against Coveron directly. Your claim goes to HSB Specialty Insurance Company, a licensed insurer, so the payout is backed the same way an actual insurance policy is, not just a company promise. Here are the exact amounts covered by each Coveron plan:
Feature
Scam Protection
Identity Theft Protection
Full Protection / Family Plans
Identity theft insurance
No
$2 million
$2 million
Cyber extortion insurance
No
$100,000
$100,000
Home title fraud insurance
No
$100,000
$100,000
Online fraud insurance
$100,000
$100,000
$100,000
Cyberattack insurance
$10,000
$10,000
$10,000
The cyber extortion coverage is worth paying attention to as well. It’s easy to assume that risk only applies to businesses, but people experience cyber extortion as well. It could be one of your devices getting infected with ransomware, meaning your device gets locked down unless you pay a ransom, or someone finds personal information you don’t want public. Regardless, if someone’s trying to extort you online, Coveron can help.
Filing a claim connects you with recovery support to help walk through the process. HSB assigns a dedicated recovery specialist to guide you through the process. Some competitors offer an in-house expert instead of outsourcing it to their insurance provider. If that’s what you’re looking for, we cover a few in our best restoration services list. We know this can be confusing, so we made an identity theft insurance guide that goes over how these payouts typically work across the industry in simple terms.
We appreciate that Coveron includes NordVPN, one of our favorite VPNs, in its top-tier plan
If you’re already juggling separate subscriptions for a VPN, antivirus, and a data removal service, Full Protection folds all three into one bill instead of three. We recommend each of those services as they can help reduce your identity theft risks. A VPN keeps your traffic private on public networks, antivirus catches malware before it can harvest your data, and Incogni works to get your information removed from the data broker sites that often feed identity theft in the first place. None of these tools stop identity theft by themselves, but together they shrink how much of your data is exposed in the first place.
We were impressed with the quality of these bundled tools. When we tested Aura, we found their VPN and data removal service offered fewer features than NordVPN and Incogni, although the antivirus was comparable. That held true when we tested LifeLock as well, except their antivirus stands above the rest.
Overall, we liked Coveron’s service when testing it for a full month. It offers great value as long as you’re willing to commit to one of their long-term plans. In particular, we find its best suited for those who fit one of the following three categories:
Budget-conscious shoppers who still want real insurance backing: A $2 million insurance policy at under $6.50 per month is one of the stronger insurance-to-price ratios we’ve seen.
Anyone worried about cyber extortion specifically: This is a coverage category most competitors don’t call out on its own.
Existing Nord Security users: if you already use NordVPN or Incogni, Full Protection’s bundle may help you save money on tools you’re already paying for elsewhere.
It’s a weaker fit if you prioritize credit monitoring and reporting, or if you specifically need a month-to-month family plan. Neither is available here.
Bottom Line
Coveron’s insurance figures and cyber extortion coverage carry the service, even without a flashy brand name behind them. Just be deliberate about which tier you pick. Scam Protection looks like a bargain but skips the insurance and credit monitoring most people are actually shopping for, while Identity Theft Protection and Full Protection are where the service earns its reputation. It offers great value, although there are some surprising tradeoffs like an annually updated credit score on the top-tier plan and a combined insurance limit on family plans.
Yes. Coveron is a rebrand of NordProtect, the same Nord Security service under a new name. Existing subscribers were moved over automatically, and only billing statements reflect the change.
Yes, through two dedicated plans, Full Couple Protection (2 adults plus unlimited children) and Full Family Protection (up to 5 adults plus unlimited children). Both include the same coverage as the individual Full Protection plan, just extended to more people. Per Coveron’s own FAQ, the $2 million insurance limit is shared across the plan rather than per person.
Identity Theft Protection is the cheapest tier that includes identity theft insurance, starting at $4.99/month on a 2-year term. Scam Protection, Coveron’s entry tier, doesn’t include identity theft insurance or credit monitoring at all.
Only on Full Protection and the family plans. Identity Theft Protection includes 1-bureau (TransUnion) credit monitoring. You need to move up to Full Protection, Full Couple Protection, or Full Family Protection for 3-bureau coverage.
No. Coveron’s standalone service, including its insurance benefits, is available only to U.S. residents, and insurance benefits specifically aren’t available to New York residents.
 Updated September 21, 2026
copied!